
Table of Contents Show
Last Updated: September 2026
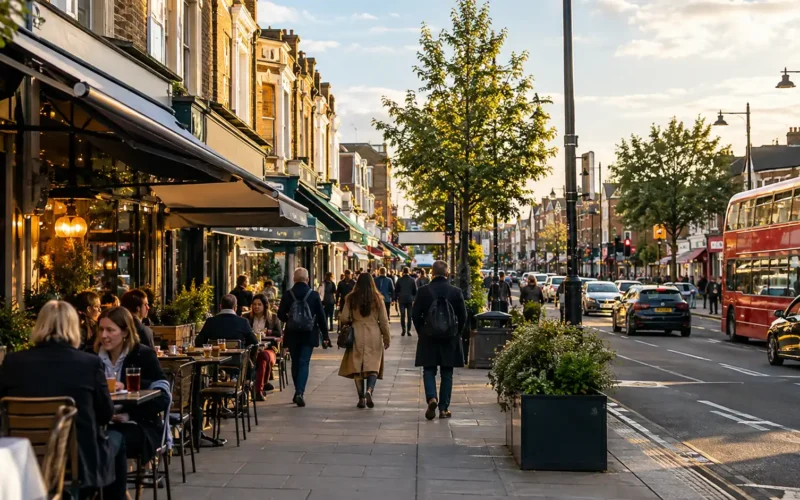
Remote work has changed where and when Londoners spend their money, but the effect on Outer London has turned out to be more complicated than simply moving customers from the city centre to suburban high streets.
During the early years of home working, there was a widespread expectation that fewer journeys into Central London would mean more coffees, lunches, groceries and other purchases close to home. Some of that shift did happen. However, newer evidence shows that the gains have been uneven, with supermarkets benefiting more clearly than many independent hospitality businesses.
The latest London footfall figures add another twist. Outer London high streets and town centres did not continue experiencing universal post-pandemic footfall growth during 2025. Visitor numbers softened in many locations even while purchasing activity remained comparatively resilient.
The result is a new pattern for London: work, commuting and spending are no longer concentrated as heavily around the traditional five-day office week, but neither have they simply transferred to neighbourhood high streets.
What Has Happened to Outer London Footfall?
 The clearest recent evidence comes from the Greater London Authority’s State of London data.
In 2025, only 32% of Outer London high streets and town centres experienced an increase in daytime visitor footfall compared with 2024. For nighttime visitors, the proportion was even lower at 23%.
Across Outer London, the average change in visitor numbers between 2024 and 2025 was -5.5%.
That represents a noticeable change from 2024, when more than 90% of London areas recorded year-on-year growth.
However, footfall does not tell the entire story.
Despite fewer visitors in many places, 63% of Outer London retail areas recorded an increase in the number of daytime purchases in 2025, while 59% experienced increased nighttime purchasing.
This creates an interesting situation: fewer people passing through does not necessarily mean fewer transactions.
Outer London High Streets: The 2025 Picture
| Measure | Outer London |
|---|---|
| Areas with increased daytime visitor footfall | 32% |
| Areas with increased nighttime visitor footfall | 23% |
| Average visitor footfall change | -5.5% |
| Areas with increased daytime purchases | 63% |
| Areas with increased nighttime purchases | 59% |
The figures suggest that London’s post-pandemic recovery has entered a different stage. Instead of rapid increases in activity, many high streets appear to be settling into new patterns of use.
Remote Work Did Shift Spending Away From Central London
Hybrid working has nevertheless produced a measurable change in where office workers spend money.
Research from Centre for Cities comparing spending in 2019 and 2024 found that Central London accounted for 36% of city-centre workers’ weekday in-person spending in 2019.
By 2024, that share had fallen to 29%.
The reduction was visible across every weekday, although Friday experienced a particularly pronounced decline.
That makes sense in the context of hybrid working. Employees who previously travelled into Central London five days a week may now make that journey only part of the week.
Every missed commute can potentially remove several transactions from the centre: breakfast near the station, coffee near the office, lunch, an after-work drink or an unplanned purchase on the journey home.
But where did that money go?
The answer is more complicated than many expected.
Outer London Did Not Receive All the Spending Lost by the Centre
One of the most important findings for understanding Outer London’s changing foot traffic is that reduced Central London spending has not translated into an equivalent boom in neighbourhood spending.
Workers are spending a larger share of their money near home than before the pandemic, but the increase has been relatively modest.
That means a pound no longer spent near a Central London office does not necessarily become a pound spent on an Outer London high street.
There are several possible destinations for that spending.
A worker at home might make lunch rather than buy it. Online shopping can replace a lunchtime retail visit. A weekly supermarket shop may replace several smaller purchases. Some spending can simply disappear because commuting itself previously created reasons to buy.
This distinction is important when discussing the economic effects of remote work.
Less Central London spending does not automatically equal more Outer London spending.
Supermarkets May Be Bigger Winners Than Local Cafés
Early predictions about remote working often imagined neighbourhood cafés filled with laptop users and local restaurants benefiting from workers staying close to home.
There is some evidence of additional local spending, but grocery shopping has produced a much clearer shift.
Centre for Cities found that supermarkets appeared to be among the biggest suburban beneficiaries of changed worker spending patterns.
The shift towards local pubs, cafés and eateries was considerably more modest.
There is a practical explanation.
Someone working from home may walk to a supermarket for groceries but then prepare breakfast or lunch themselves. That creates local economic activity without producing the same spending pattern as an office worker buying breakfast, coffee and lunch in Central London.
So remote work can increase someone’s presence in their neighbourhood without generating a proportional increase in high-street hospitality spending.
Why Footfall and Spending Can Move in Different Directions?
The 2025 Outer London figures highlight an important point: footfall and consumer spending should not be treated as the same measurement.
Imagine a high street attracting 10% fewer visitors but the remaining customers visit with a clearer intention to buy. Transactions could remain stable or even increase.
The opposite can also happen. A busy transport interchange may generate enormous foot traffic without every person spending locally.
This helps explain why Outer London’s 2025 numbers can show falling average visitor footfall alongside purchasing growth across a majority of retail areas.
For businesses, customer quality may therefore matter as much as raw pedestrian numbers.
The Five-Day High Street Has Become a Seven-Day Puzzle
Before widespread hybrid working, commuter behaviour created relatively predictable rhythms.
Monday morning meant people travelling towards workplaces. Friday evening meant office workers meeting for drinks or dinner before heading home.
Hybrid working has disrupted that timetable.
Monday and Friday are particularly important because home working remains more common on these days than it was before the pandemic.
Central London has also experienced an interesting shift in after-work behaviour.
In 2019, Friday accounted for the largest share of Central London workers’ pub and bar spending. By 2024, Thursday had become the leading day.
Thursday has, in effect, taken on some of the economic role previously associated with Friday.
For Outer London businesses, meanwhile, the opportunity is no longer simply “capture commuters who are staying home”. Businesses increasingly need to understand what customers are doing on different days of the week.
Why Every Outer London High Street Is Different?
 It would also be misleading to treat Outer London as one market.
A major town centre such as Croydon serves a very different customer base from a small neighbourhood parade. Likewise, Wembley, Ilford, Hounslow, Wood Green and Purley have different catchments, transport connections, visitor flows and spending patterns.
New research into London’s suburban high streets reinforces this point.
Centre for Cities analysed 545 suburban London high streets and found that their performance is influenced by three particularly important characteristics:
1. The Size of the Customer Catchment
A high street serving hundreds of thousands of potential customers has a fundamentally different economic base from a small local shopping parade.
Larger catchments tend to generate stronger demand because businesses have access to more potential customers.
2. How Much Local Customers Earn
Population alone is not enough.
The spending power of people within a high street’s catchment can have an even greater influence on commercial demand.
Two locations can have similarly sized populations while producing very different retail outcomes if disposable incomes differ significantly.
3. Visitors From Outside the Area
Tourism and major attractions can provide another layer of demand.
Wembley provides an obvious example. Events and international visitors can generate customers who would not otherwise form part of the normal neighbourhood market.
This means remote working is only one factor shaping Outer London foot traffic.
Housing, population density, income, transport, tourism, retail mix and major attractions can be equally important — and sometimes more important.
London’s Suburban High Streets Are More Resilient Than They May Appear
Declining footfall might suggest that suburban retail is entering a broad downturn, but vacancy data paints a more nuanced picture.
Research published in late 2025 found that the median suburban London high street had a vacancy rate of approximately 8% to 10%.
More significantly, 78% of London’s suburban high streets had vacancy rates below the UK city-centre average used in the research.
Primary suburban high streets recorded a slightly higher median vacancy range of 10% to 12%, but even among these larger centres, 76% had vacancy rates below the national city-centre average.
That suggests London’s suburban high streets retain substantial underlying demand even when short-term visitor numbers fluctuate.
Remote Working Has Changed the Purpose of Some Local Trips
One less obvious effect of remote work is the way it changes why people use their neighbourhood.
A commuter may previously have left home at 7:30am and returned after 6pm. During those hours, almost all weekday spending opportunities occurred somewhere else.
A home-working day changes that geography.
The same resident may now use the local pharmacy at lunchtime, collect a parcel during the afternoon, visit a supermarket before dinner or arrange a coffee close to home.
These are small behavioural changes individually.
Repeated across thousands of residents, however, they can alter the types of businesses that receive weekday demand.
This may explain why businesses built around practical neighbourhood needs can respond differently to hybrid working than businesses heavily dependent on discretionary spending.
Remote Work Is Only Part of the Outer London Story
It is tempting to explain every post-pandemic change in footfall through working from home.
The evidence increasingly suggests that this is too simplistic.
Remote and hybrid working influence when people travel and where workers make some purchases, but the health of an Outer London high street also depends on the economic strength of its surrounding area.
Recent research suggests that catchment income, population size and visitor numbers are major influences on demand for suburban high-street space.
That creates an important distinction.
Remote working changes where people are during the day. Local economic conditions influence how much they are able and willing to spend while they are there.
The two effects should not be confused.
What Could Outer London High Streets Look Like Next?
The most likely long-term change is not the disappearance of Central London or the complete revival of every suburban high street.
Instead, London appears to be becoming more geographically and temporally complicated.
Central London remains a powerful employment, leisure and spending destination, particularly during the middle of the working week.
Outer London continues to benefit from millions of residents conducting everyday life closer to home, but the commercial effect varies dramatically between neighbourhoods.
Retailers may therefore increasingly need to think about when customers arrive as well as how many arrive.
A café near a station may face a different Monday from its pre-2020 experience. A supermarket may receive more weekday neighbourhood spending. A pub may find Thursday more commercially significant than Friday. A local service business may gain customers simply because residents are physically present during working hours.
Those differences are becoming part of London’s normal economic geography rather than a temporary response to the pandemic.
What the Latest Data Really Tells Us?
The remote-work story in Outer London has evolved.
The first stage was dramatic: millions of workers stopped commuting and neighbourhood activity suddenly became much more important.
The second stage brought office returns and the emergence of hybrid schedules.
London now appears to be entering a third stage in which these behaviours are becoming embedded, while high streets adjust to a less predictable mix of workers, residents and visitors.
The 5.5% average decline in Outer London visitor footfall between 2024 and 2025 shows that suburban activity cannot simply be assumed to keep growing because hybrid work exists.
At the same time, increasing purchases across many Outer London retail areas and comparatively low suburban vacancy rates show that declining footfall does not automatically mean high-street decline.
The bigger change may therefore be redistribution rather than relocation.
Remote work has redistributed trips across the week, redistributed some spending between Central and Outer London, and changed which types of businesses capture that spending.
For Outer London’s high streets, understanding those new patterns could prove far more useful than simply counting how many commuters stay home.
Final Thoughts
Remote work has undoubtedly altered London’s economic map, but its legacy is more subtle than the idea of workers simply abandoning the centre for their local high street.
Outer London now receives some spending that previously occurred closer to offices, particularly on home-working days. Yet supermarkets have captured a significant part of that shift, while many hospitality businesses have seen more modest benefits.
Meanwhile, 2025 brought weaker visitor footfall across many Outer London locations even as purchasing activity remained resilient.
For local businesses, that makes the next phase less about waiting for more people to work from home and more about understanding the new rhythm of their neighbourhood: who visits, when they arrive, why they come and what they actually buy.
That may be the most lasting high-street change created by London’s remote-working experiment.
FAQs
Has Remote Working Increased Foot Traffic in Outer London?
Remote and hybrid working have increased the amount of time some employees spend close to home, but recent data does not show a universal increase in Outer London footfall. Average visitor footfall in Outer London declined by 5.5% between 2024 and 2025.
Has Working From Home Increased Spending on Local High Streets?
There has been some shift towards spending closer to home, but research indicates that the increase has been modest. Grocery spending appears to have shifted more strongly than spending at cafés, pubs and restaurants.
Are Outer London High Streets Struggling?
Performance varies considerably by location. Despite weaker visitor footfall in 2025, many retail areas recorded increased purchases, while London’s suburban high streets generally have comparatively low vacancy rates.
Which Businesses Have Benefited Most From Hybrid Working?
Evidence suggests suburban supermarkets have been among the clearest beneficiaries of changing worker spending patterns. The benefit to independent cafés, restaurants and pubs has been less pronounced than early predictions suggested.
Is Central London Losing Spending to Outer London?
Central London’s share of weekday in-person spending by city-centre workers fell from 36% in 2019 to 29% in 2024. However, only part of this appears to have shifted to workers’ home neighbourhoods, meaning the relationship is not a simple transfer from Central to Outer London.